All Categories
Featured


New Policies for HIV Positive Applicants
Table of Contents
Understanding how carrier monetary strength and underwriting hunger connect to each other is also essential context our resource on what an insurance coverage business's AM Finest rating indicates covers the financial strength measurement, and our resource on how do insurance coverage brokers make money covers why independent broker access to several providers consistently produces much better outcomes after a decline than using to a single provider based upon name recognition.
Simplified concern policies, which use health questions without a complete paramedical exam and prescription database review, are more available for profiles that struggle in totally underwritten lanes while still offering significant survivor benefit quantities at specified premiums. Guaranteed problem policies, which need no health info, supply last expenditure coverage with graded benefits for the preliminary period.
Underwriting guides for typical disqualifier categories and alternative coverage structures. Specialized underwriting resources for specific conditions, visa profiles, and coverage timing decisions.
Impaired threat life insurance, also known as high-risk life insurance, is a possibility for those who believe they might have problem receiving protection. It uses protection options to individuals who do not fit into the standard score classifications for standard life insurance coverage policies. Due to higher threat the premiums are often high and some policy alternatives might offer lower coverage quantities, but you still have options to protect protection for your liked ones.
Each service provider has its own guidelines, but high-risk habits and conditions might include: Your present health, previous diagnoses, and how well serious conditions are managed are some of the main aspects insurance providers consider to identify the threat in guaranteeing you. Some typical health conditions that frequently fall under impaired risk consist of: Type 1 or Type 2 DiabetesHeart Illness or previous heart attackHigh blood pressureCancer historyStroke or other neurological conditionsAsthma, COPD or other breathing issuesMental health conditions like anxiety or anxiety Aside from health aspects, your everyday practices might likewise affect your life insurance eligibility, approval, protection quantity and premiums.
Goldencare vs Harmony SoCalNew Policies for HIV Positive Applicants
These consist of: RoofersConstruction workers Pilots or air travel professionalsOil rig workersEmergency responders like firefightersWhen someone has one (or more) lifestyle factors or higher-risk conditions, it can affect the ability to get a policy and the premium prices. Impaired danger life insurance coverage works the very same way as a conventional policy. It is designed to use a death benefit to your loved ones after you die, however what makes it various is the underwriting process.
: Well managed health conditions can assist you qualify for lower rates in contrast to when insurance providers determine patterns of negligence around medication, follow-up and treatment plan. Smokers normally pay more premium in contrast to non-smokers. High-risk task functions indicate a higher opportunity of injury or accidents, so exceptional expenses might increase.
Each insurance provider has its own classification system, but generally, the 5 classifications are: People with excellent psychological and physical health, no weight concerns, and general very few risk elements. A little percentage of people receive this.: Overall great physical and psychological health but may have small threat, such as being a little obese.
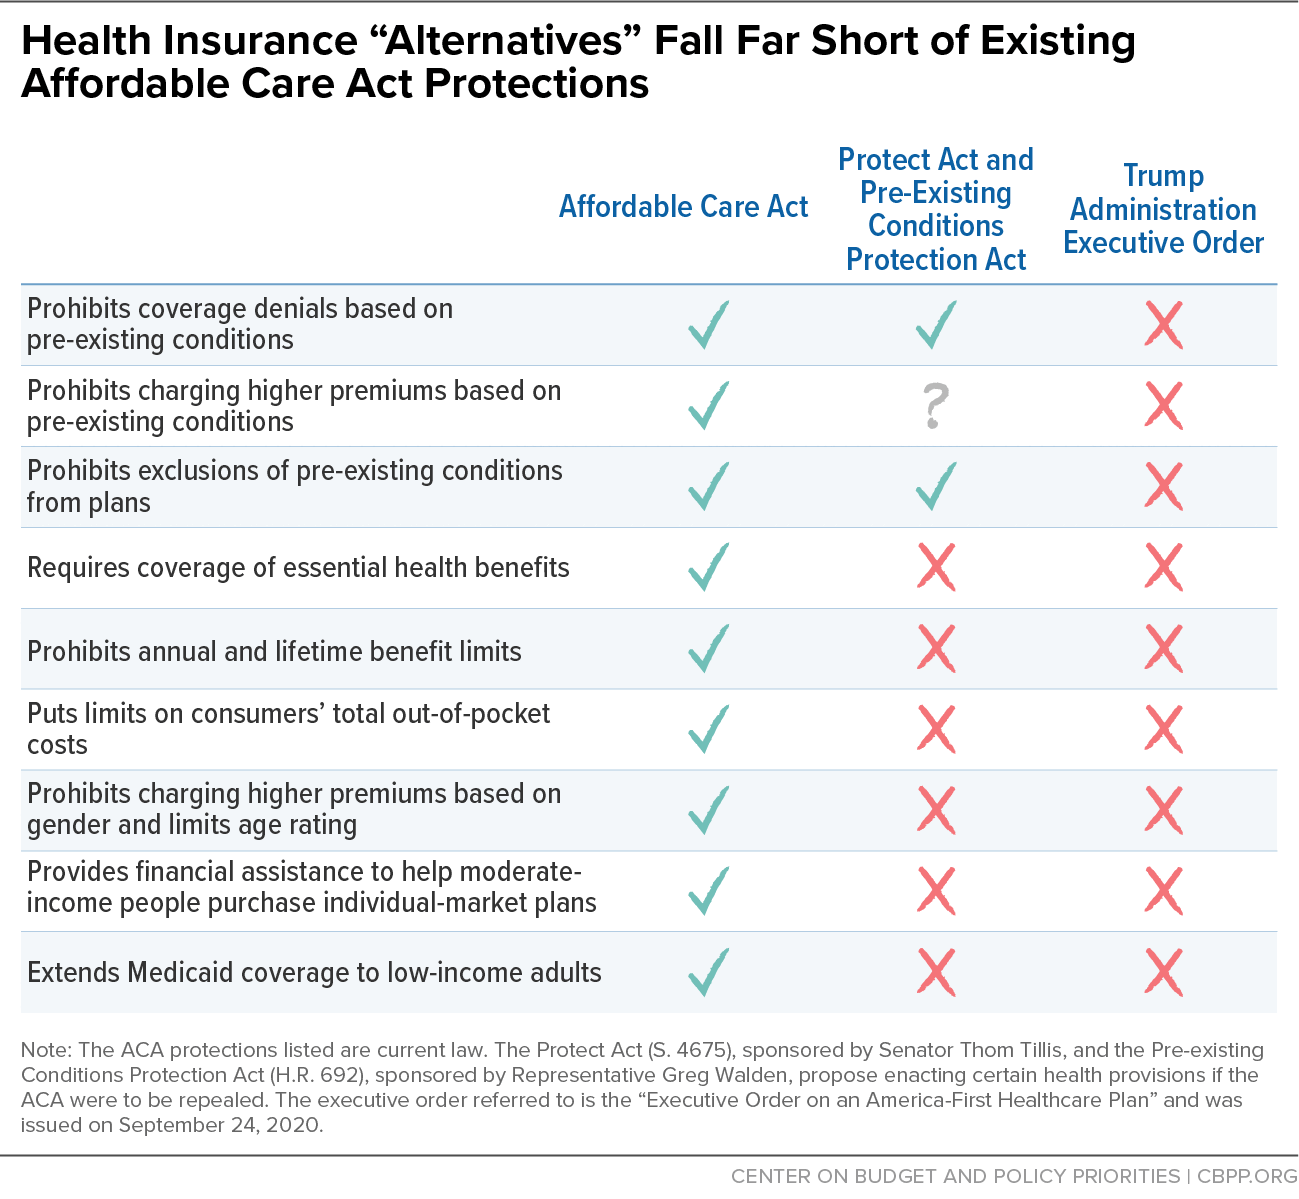
A pre-existing health condition does not imply you can't get approved for a life insurance policy, but it simply impacts your readily available alternatives and rates. Severe conditions such as cancer or a past heart attack might place you in a higher-risk category, many individuals presume that they don't get approved for protection.
Integrating Life Insurance with Special Needs Trust Planning
You still have alternatives and that's when impaired threat life insurance coverage comes into the picture. Keep in mind: You can get life insurance coverage with a medical condition.
Whether you have medical or non-medical high-risk elements, you still likely have choices. The key is to match the policy options to your goals and present financial or personal circumstances. In case of impaired conditions, getting coverage is much easier through no-medical-exam choices that may be much easier to receive than fully underwritten term or long-term life insurance coverage policies.
It is a practical option for those with critical health problems seeking ensured approval but at a higher premium and lower coverage amount.
The expenses are frequently lower than ensured problem policies but greater than traditional completely underwritten policy types. Term life insurance offers protection for a set period of 10-40 years that stays the very same throughout the policy's term. It can be an appropriate alternative for those seeking economical coverage for short-lived needs and covering major monetary obligations.
Empathy-Driven for Special Risk
Entire life insurance offers lifelong protection with money worth build-up. It frequently comes at a higher cost and those with relatively stable health conditions who don't mind going through a medical test might open higher protection. But particular versions like last expenditure insurance coverage may appropriate for covering smaller sized coverage requirements. Not all insurance providers might offer comparable coverage choices and ensured problem is not your only alternative. Different insurance providers may assess threat differently, so constantly compare quotes.
Timing matters, so wait if your condition is improving to get approved for much better alternatives later. Do not use with too lots of insurance providers at the same time. Last but not least, be honest and transparent in your application to avoid claim denials later. Even as an impaired-risk candidate, you may still be able to get coverage.
Here are some tips you might follow: Ensure that your condition is well handled and you follow the treatment plan. Keep your medical records helpful to reveal stability in your health. Attempt giving up dangerous way of life habits like cigarette smoking or alcohol intake. Handle healthy lifestyle habits for weight management. Avoid using right away after a condition is identified.
Download and complete any relevant questionnaires suggested based off the preliminary questionnaire.
Life insurance coverage can be complicated, particularly when it concerns underwriting. Many individuals have a hard time to understand the procedure and are often deceived by typical misconceptions. This post seeks to clarify life insurance underwriting by presenting clear, precise information to assist you make informed decisions. It has actually typically been stated that underwriting is an extremely sophisticated and time-consuming process.
Why Custom Risk Underwriting Matters in 2026
Most business now use quick underwriting options, which allow you to lessen the time needed to get insured. This indicates you might get protection the fastest way without jeopardizing on thoroughness in its appraisal. Stay ahead of the market with special feature stories on the top business, professional insights and the latest news delivered directly to your inbox.
While it's real that health plays a large role in underwriting, insurance companies think about many factors, consisting of age, way of life, and family case history. Even if you have some health issues, you can still find competitive rates tailored to your circumstance. It's everything about discovering the right policy that matches your requirements and circumstances.
Each policy type, the quantity of coverage you want, and the scrutiny will depend on it. For many policies, especially those with lower coverage quantities, the process can be simple and does not require much time. Some even offer no-exam policies, which count on existing medical records and other data and make decisions based on that.

Latest Posts
Current Guidelines for HIV Health Insurance

Policy Planning for Disabled US Families
New Policies for HIV Positive Applicants